
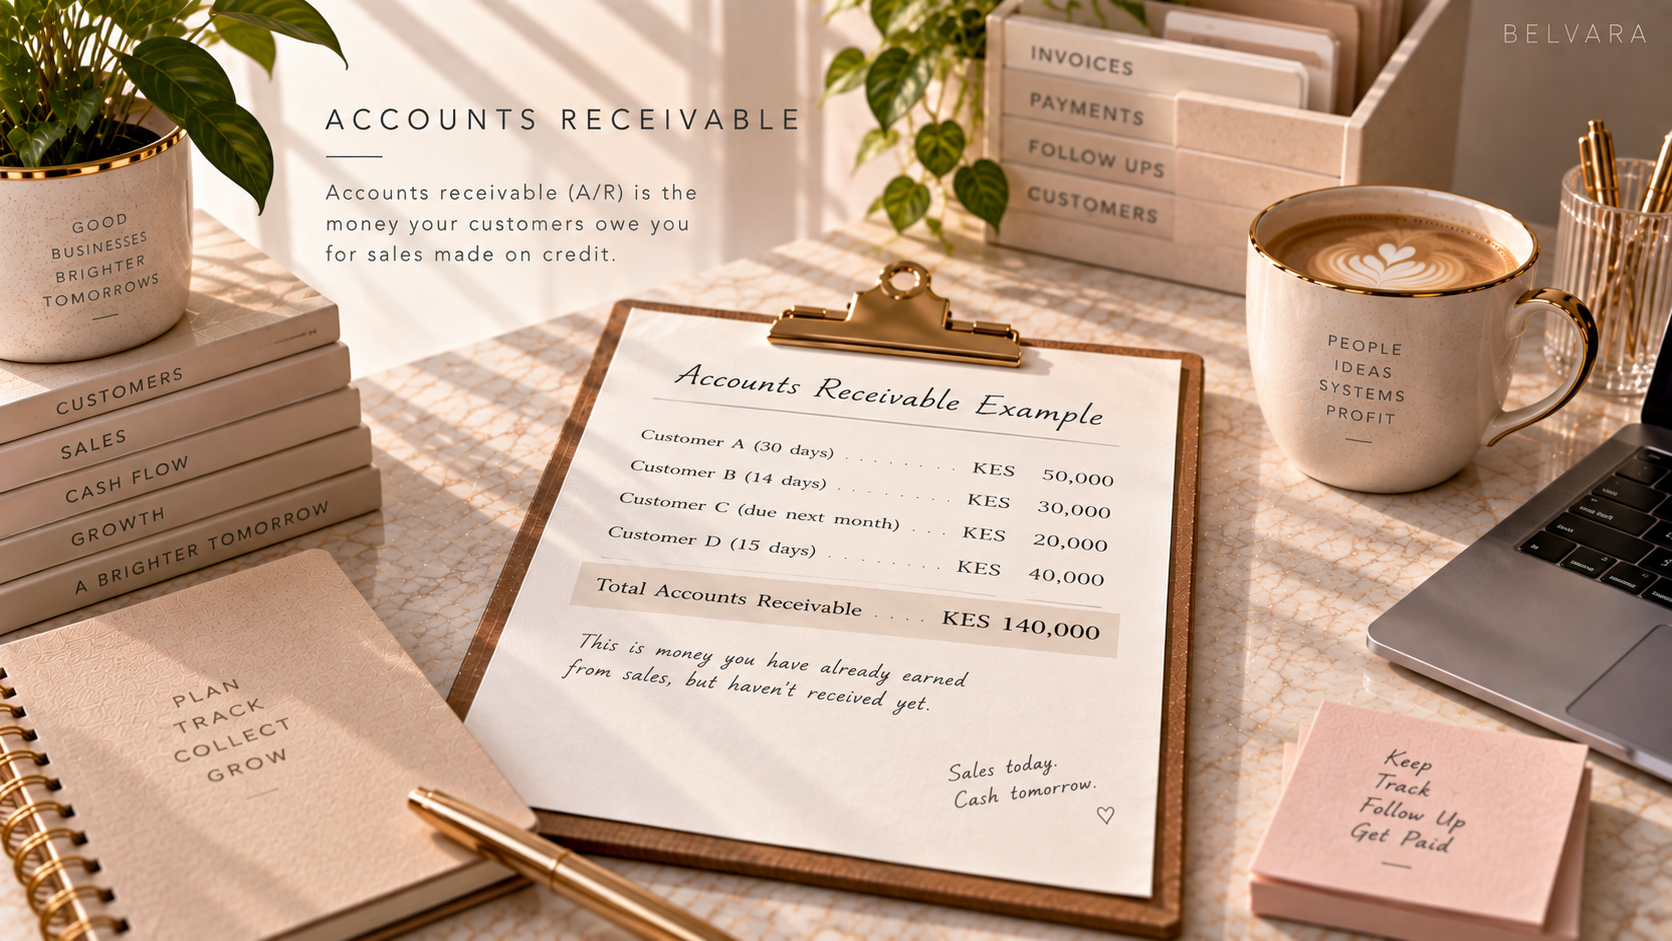
You made the sale. The customer has the product. You still don’t have the money.
The invoice says KES 500,000.
Revenue says you sold KES 500,000.
The customer already received what they bought.
But your bank account is still waiting.
Meanwhile, your supplier wants to be paid.
Payroll is coming.
Stock needs replacing.
That unpaid KES 500,000 is accounts receivable.
And until it becomes cash, your customer is effectively holding part of your working capital.
Accounts receivable, often shortened to A/R, is money customers owe your business for goods or services you have already provided on credit.
It is an asset.
But it is not cash.
And the longer it stays unpaid, the more dangerous it becomes to treat it like cash.
Belvara view: A sale is not finished just because the invoice exists. Until the money arrives, part of the business is still sitting inside the customer’s promise to pay.
What are accounts receivable?
Accounts receivable are amounts customers owe a business for goods or services already provided but not yet paid for.
Suppose your business delivers goods worth:
KES 100,000
to a customer today.
You give the customer:
30 days to pay
The business may recognise the sale now, depending on the accounting treatment and when the revenue recognition conditions are met.
But the cash has not arrived.
Instead, the business records:
KES 100,000 accounts receivable
The customer owes you.
That receivable is an asset because the business expects to collect cash in the future.
When the customer pays:
- cash increases
- accounts receivable decreases
The sale does not happen again.
The receivable simply becomes cash.
A simple accounts receivable example
Suppose you sell goods to three customers on credit.
Customer A owes:
KES 120,000
Customer B owes:
KES 80,000
Customer C owes:
KES 50,000
Total accounts receivable:
KES 250,000
That means customers collectively owe the business KES 250,000.
Now suppose the bank balance is only:
KES 70,000
The business may have:
KES 320,000
between cash and receivables.
But only KES 70,000 is immediately available.
The other KES 250,000 still has to be collected.
Accounts receivable can make the balance sheet look stronger before the bank account feels stronger.
Accounts receivable are assets
Accounts receivable are generally classified as current assets when the business expects to collect them within the normal operating cycle or short-term period.
Why are they assets?
Because they represent a right to receive economic value from a customer.
But not all assets are equally liquid.
Cash can usually be used immediately.
Receivables have to be collected first.
That difference matters when bills are due now.
Accounts receivable are not cash
This sounds obvious.
Businesses still get trapped by it.
Suppose your monthly numbers show:
- Revenue: KES 2,000,000
- Accounts receivable created: KES 1,200,000
- Cash collected from those sales so far: KES 800,000
The P&L may show KES 2 million of revenue.
The bank account did not receive KES 2 million.
If the owner spends as though every sale has already turned into cash, the business can create a cash shortage while still reporting strong revenue.
Belvara view: Revenue can arrive before cash does. Your bills usually do not care which one arrived first.
Accounts receivable vs revenue
Revenue and accounts receivable are related.
They are not the same thing.
Revenue records income earned from selling goods or services when the relevant accounting conditions are met.
Accounts receivable records the amount the customer still owes.
Suppose you complete a credit sale for:
KES 200,000
The business may recognise:
- Revenue: KES 200,000
- Accounts receivable: KES 200,000
When the customer later pays:
- Cash increases by KES 200,000
- Accounts receivable decreases by KES 200,000
Revenue does not increase again when payment arrives.
That is why collecting a receivable is different from making a new sale.
Accounts receivable vs accounts payable
These terms are easy to mix up.
Accounts receivable = customers owe you.
Accounts payable = you owe suppliers.
A simple way to remember it:
Receivable: money should be received.
Payable: money needs to be paid.
| Accounts receivable | Accounts payable | |
| Who owes? | Customer owes the business | Business owes supplier |
| Balance sheet type | Asset | Liability |
| Cash effect later | Cash comes in | Cash goes out |
| Main risk | Customer pays late or never | Business pays late or cannot settle |
Both can exist at the same time.
That is where working-capital pressure becomes real.
Your customer can owe you while your supplier is already asking to be paid
Suppose:
You sell stock for:
KES 500,000
on 60-day customer terms.
The stock cost:
KES 300,000
Your supplier wants payment in:
30 days
The sale may be profitable.
The customer still owes you KES 500,000.
But your supplier wants KES 300,000 before the customer is required to pay.
You now have a timing problem.
The business funded the customer’s credit.
A profitable credit sale can still create a cash crisis if the customer gets more time than your supplier gives you.
Credit terms create a financing decision
When you allow a customer to pay later, you are doing more than making a sale.
You are giving the customer time.
That time has value.
Suppose two customers buy the same KES 200,000 order.
Customer A pays immediately.
Customer B pays in 60 days.
Same revenue.
Same selling price.
Very different cash timing.
For 60 days, the business has to carry Customer B.
That can affect:
- supplier payments
- payroll
- stock replenishment
- rent
- taxes
- working capital
- borrowing needs
Credit can help close bigger sales.
It can also make the business finance its customers.
A bigger sale is not always a better sale
Suppose:
Customer A
- Sales this month: KES 300,000
- Pays immediately
- No overdue balance
Customer B
- Sales this month: KES 800,000
- Owes KES 1,400,000
- Oldest invoice is 90 days overdue
Customer B creates more revenue.
Customer A creates cleaner cash.
That does not automatically make Customer B a bad customer.
But revenue alone should not crown Customer B the best customer.
Belvara view: Your biggest customer can also be the customer holding the biggest piece of your cash.
Accounts receivable and cash flow
Accounts receivable are one of the clearest reasons profit and cash flow can tell different stories.
Suppose:
- Revenue: KES 1,000,000
- Expenses: KES 800,000
- Profit: KES 200,000
Looks healthy.
But suppose:
KES 700,000 of the revenue is still unpaid
The business may report profit.
Cash can still be tight.
The business still needs money for:
- suppliers
- staff
- operating expenses
- tax
- stock
Profitability does not eliminate collection risk.
Accounts receivable and working capital
Accounts receivable are part of current assets and therefore part of working capital.
A common formula is:
Working Capital = Current Assets − Current Liabilities
Suppose:
Current assets
- Cash: KES 200,000
- Receivables: KES 800,000
- Inventory: KES 1,000,000
Total current assets:
KES 2,000,000
Current liabilities
KES 1,400,000
Working capital:
KES 600,000
Positive.
But now inspect the current assets.
Most of the value is not cash.
If receivables are late and inventory moves slowly, the business can still struggle to meet short-term obligations.
A positive working-capital number can hide bad collections.
The age of receivables matters
KES 1 million owed by customers tells you less than you think.
You need to know how old the debt is.
Suppose total receivables are:
KES 1,000,000
Split like this:
- Not yet due: KES 400,000
- 1–30 days overdue: KES 250,000
- 31–60 days overdue: KES 150,000
- 61–90 days overdue: KES 100,000
- More than 90 days overdue: KES 100,000
The total is still KES 1 million.
But the quality of that KES 1 million is not equal.
A balance due next week is different from one that has been ignored for four months.
What is an accounts receivable ageing report?
An accounts receivable ageing report groups unpaid customer balances by how long they have been outstanding.
A typical structure might look like:
| Customer | Current | 1–30 days overdue | 31–60 days | 61–90 days | 90+ days |
| Customer A | KES 100,000 | KES 0 | KES 0 | KES 0 | KES 0 |
| Customer B | KES 0 | KES 80,000 | KES 0 | KES 0 | KES 0 |
| Customer C | KES 0 | KES 0 | KES 50,000 | KES 0 | KES 0 |
| Customer D | KES 0 | KES 0 | KES 0 | KES 0 | KES 120,000 |
The ageing report helps answer:
- Who owes us?
- How much?
- When was it due?
- Which balances are becoming risky?
- Which customers need follow-up first?
A single A/R total cannot answer those questions.
Overdue receivables are not just an accounting problem
Late customers create operational consequences.
The business may:
- delay supplier payments
- postpone stock purchases
- borrow
- use owner cash
- miss opportunities
- reduce marketing
- struggle with payroll
- delay expansion
The original sale may still look profitable.
The collection delay can make the business behave like it is not.
An unpaid invoice can turn your customer’s cash-flow problem into yours.
The longer a receivable stays unpaid, the less comforting it becomes
An invoice one day overdue is not the same as an invoice 180 days overdue.
As time passes:
- collection can become harder
- customer circumstances can change
- disputes can emerge
- contact can disappear
- the chance of full recovery can weaken
This is why receivable ageing matters more than the headline total.
Bad debts
Sometimes a customer does not pay.
The business may eventually determine that some or all of the receivable cannot be collected.
That can result in a bad-debt loss or other accounting adjustment, depending on the applicable accounting treatment.
Suppose the business records:
KES 200,000 receivable
from a customer.
The customer later collapses financially and the business expects to recover only:
KES 50,000
The original KES 200,000 asset no longer tells the full economic truth.
Receivables are assets because cash is expected.
When that expectation weakens, the asset needs harder scrutiny.
Allowance for doubtful accounts
Financial reporting can require businesses to recognise expected credit losses rather than waiting until every bad debt is completely certain.
The exact accounting requirements depend on the applicable financial reporting framework and circumstances.
The management principle is simple:
Do not treat every shilling customers owe as equally collectible.
A receivable from a customer who always pays on time is not the same as a 180-day-old disputed balance.
Partial payments can hide overdue risk
Suppose a customer owes:
KES 300,000
They pay:
KES 50,000
The business celebrates the payment.
But:
KES 250,000 remains outstanding
Partial collection is useful.
It does not reset the commercial reality of the unpaid balance.
The owner still needs to know:
- original invoice amount
- amount collected
- remaining balance
- due date
- age of remaining balance
- agreed payment schedule
Payment plans change the collection question
Sometimes the business intentionally allows instalments.
Suppose a customer owes:
KES 120,000
under an agreed four-month payment arrangement.
Expected payment:
KES 30,000 per month
If the customer pays according to schedule, the outstanding receivable is not necessarily a problem.
But the business still needs visibility over:
- what has been paid
- what remains
- what is due next
- missed instalments
- revised arrangements
A controlled payment plan is different from an invoice nobody is chasing.
Accounts receivable and discounts
Businesses sometimes offer early-payment discounts.
For example:
“Pay within 7 days and receive a small discount.”
This can reduce the amount collected.
But it may also accelerate cash.
Whether that trade-off makes sense depends on:
- margin
- cash needs
- customer behaviour
- cost of financing
- size of discount
The business should compare what it gives away with what faster cash is worth.
Accounts receivable and late-payment penalties
Some businesses include late-payment charges in customer terms.
Whether and how such charges can be applied depends on the contract, applicable law and the circumstances.
They should not be treated as a substitute for good credit control.
A penalty written into an invoice is not useful if the business never follows up or cannot enforce the agreement.
Revenue can grow while collections get worse
Suppose:
Month 1
- Revenue: KES 1,000,000
- Receivables: KES 200,000
Month 6
- Revenue: KES 2,000,000
- Receivables: KES 1,200,000
Revenue doubled.
Receivables increased six times.
That does not automatically mean the business is unhealthy.
The business may have deliberately moved into wholesale or larger credit customers.
But it deserves investigation.
The business may be growing by leaving more money with customers.
Sales growth feels different when customers are holding most of the growth in unpaid invoices.
Accounts receivable turnover
Accounts receivable turnover is one measure used to understand how efficiently a business collects credit sales.
A common formula is:
Accounts Receivable Turnover = Net Credit Sales ÷ Average Accounts Receivable
Suppose:
- Annual net credit sales: KES 12,000,000
- Average accounts receivable: KES 2,000,000
A/R turnover:
6 times
This suggests the average receivable balance turned over about six times during the period.
The figure needs context.
Different industries and customer terms produce different collection patterns.
Days Sales Outstanding
Days Sales Outstanding, often shortened to DSO, estimates the average number of days it takes a business to collect receivables.
A common formula is:
DSO = Average Accounts Receivable ÷ Net Credit Sales × Number of Days
Suppose:
- Average accounts receivable: KES 2,000,000
- Annual net credit sales: KES 12,000,000
- Period: 365 days
DSO:
KES 2,000,000 ÷ KES 12,000,000 × 365 ≈ 61 days
That means collections are taking about 61 days on average in this simplified example.
If customer terms are 30 days, a 61-day DSO deserves attention.
If normal terms are 60 days, the interpretation is different.
A collection metric is only useful when compared with the terms you actually gave the customer.
DSO can improve while one customer is becoming dangerous
Average metrics can hide concentration.
Suppose overall DSO improves.
But one customer now owes:
KES 2,000,000
and represents:
60% of all receivables
That creates customer concentration risk.
If that customer pays late, the whole business can feel it.
This is why the owner should read:
- total receivables
- ageing
- DSO
- customer concentration
together.
Customer concentration matters
Suppose total receivables are:
KES 3,000,000
One customer owes:
KES 1,800,000
That one customer controls 60% of the cash the business expects to collect.
Even if the customer has always paid, the concentration matters.
A delayed payment can create a large working-capital gap.
Credit limits
A credit limit sets the maximum amount a customer can owe at a time.
Suppose a customer has a limit of:
KES 300,000
They already owe:
KES 280,000
A new KES 100,000 order would push total exposure to:
KES 380,000
The business now has a decision.
Do you:
- stop the new credit sale?
- request partial payment?
- require the old balance to be reduced?
- increase the limit?
- approve an exception?
Without a limit, credit can grow simply because salespeople keep selling.
A credit sale increases revenue and exposure at the same time. Someone needs to be watching both.
Bigger customers can deserve tighter controls, not looser ones
Large customers often negotiate longer payment terms.
The logic sounds reasonable.
They buy more.
They are important.
Give them more flexibility.
But that can leave the business carrying a very large receivable.
Suppose:
Customer A buys:
KES 100,000 per month
on cash terms.
Customer B buys:
KES 1,000,000 per month
on 90-day terms.
By the time Customer B reaches the third month, the business could be carrying millions in exposure.
The biggest customer may deserve the most disciplined credit monitoring.
Credit sales can create fake comfort in profit
Suppose:
- Revenue: KES 2,000,000
- Gross profit: KES 800,000
- Net profit: KES 200,000
Strong month.
But customers still owe:
KES 1,500,000
The business has only:
KES 150,000 cash
The profit is real under the accounting assumptions.
The cash pressure is also real.
This is why owners should never use profit as a substitute for collection visibility.
Accounts receivable and tax timing
Tax treatment can differ from cash timing.
A business may have tax obligations related to a sale before all customer cash has been collected, depending on the tax and applicable rules.
That can create extra pressure.
For Kenya-specific VAT, income tax, eTIMS or other statutory treatment, the current rule should always be verified using authoritative KRA or legal sources before action.
The business lesson is:
Do not assume “the customer has not paid me” means every obligation connected with the sale also waits.
Accounts receivable in retail
Many retail businesses collect immediately.
But receivables can still appear when the business offers:
- customer credit
- corporate accounts
- wholesale terms
- instalment arrangements
- partial payment
- business-to-business invoicing
A retailer moving from cash sales into credit sales needs stronger collection controls.
The sale process is no longer complete at checkout.
Accounts receivable in wholesale
Receivables can be central to wholesale.
Suppose a wholesaler sells:
KES 5,000,000 per month
Most customers pay in:
30–60 days
The business may carry several million shillings in receivables at any time.
That makes:
- credit terms
- customer limits
- ageing
- collections
- supplier timing
- cash forecasting
core operating issues.
Wholesale can be profitable and still run out of cash if collections are too slow.
Accounts receivable in a service business
A service business may invoice:
- after a job
- at milestones
- monthly
- after project completion
- on retainer
- on negotiated corporate terms
Suppose a consulting business invoices:
KES 500,000
for completed work.
The customer pays 60 days later.
For those 60 days, the business has earned revenue but still has to fund:
- payroll
- software
- rent
- tax
- operations
Collections become part of service delivery economics.
Accounts receivable in SaaS
Many SaaS businesses collect subscriptions in advance.
Others invoice:
- enterprise customers
- annual contracts
- corporate accounts
- usage-based arrangements
Those invoices can create receivables.
The business should still monitor:
- billing date
- due date
- amount
- payment status
- disputes
- overdue balance
Recurring revenue does not eliminate collection risk if the customer is invoiced rather than charged automatically.

What is a good accounts receivable balance?
There is no universal ideal number.
A business with:
KES 5 million in receivables
can be healthy if:
- sales are large
- customers pay on time
- terms are deliberate
- margins are strong
- cash reserves are sufficient
A business with:
KES 300,000 in receivables
can be in trouble if:
- most balances are overdue
- one customer owes nearly everything
- suppliers are demanding cash now
- the business has little liquidity
The useful questions are:
- How much is owed?
- Who owes it?
- When was it due?
- How old is it?
- What are the agreed terms?
- What has been collected?
- How concentrated is the balance?
- How does collection timing compare with supplier timing?
- How much cash does the business need before collection arrives?
Common accounts receivable mistakes
1. Treating receivables like cash
Money owed is not money collected.
2. Looking only at the total balance
Ageing and customer concentration matter.
3. Letting invoices become overdue without follow-up
Collection usually gets harder with time.
4. Giving credit without clear terms
“Pay me when you can” is not a credit policy.
5. Giving every customer the same terms
Different customers carry different risk and buying patterns.
6. Ignoring partial-payment balances
A small payment does not erase the remaining exposure.
7. Growing revenue by growing unpaid invoices
Sales growth should be read beside collection growth.
8. Forgetting supplier timing
Customer credit can create pressure when suppliers require faster payment.
9. Confusing revenue with collection
Cash arriving later does not create revenue twice.
10. Waiting until month-end to discover who has not paid
Receivables are easier to manage before they become old.
How to manage accounts receivable better
Set clear payment terms
State:
- amount
- due date
- payment method
- deposit requirements
- instalment schedule where relevant
Invoice quickly
Every unnecessary delay before invoicing delays collection.
Track due dates
Do not rely on memory.
Use an ageing view
Separate:
- current
- 1–30 days overdue
- 31–60 days
- 61–90 days
- 90+ days
Prioritise large and old balances
Not every overdue invoice carries the same risk.
Set credit limits where appropriate
Do not allow exposure to grow invisibly.
Record partial payments properly
Always know the remaining balance.
Follow up before the invoice becomes ancient
A reminder before or shortly after the due date is easier than chasing a six-month-old invoice.
Compare collection terms with supplier terms
Do not accidentally finance customers with cash you do not have.
Review customer concentration
Know how much of total receivables depends on one customer paying.
How Belvara helps you keep accounts receivable visible
Receivables become dangerous when the sale is recorded but the remaining customer balance disappears into spreadsheets, WhatsApp messages, handwritten notes or memory.
Belvara helps keep relevant customer, sales and payment records closer together so the owner can see what was sold, what has been paid and what is still outstanding.
The goal is not another receivables total.
It is knowing which customers are holding the cash behind that total.
See what is still unpaid
A revenue number cannot tell you which part of the sale has actually been collected.
Keeping customer balances connected to sales and payments gives the owner clearer visibility over what remains.
Track partial payments
A customer may pay part now and part later.
Keeping each payment connected to the original balance makes it easier to see what is still due.
Keep overdue balances visible
The difference between a current invoice and a 90-day-old balance matters.
Ageing and due-date visibility help the owner focus attention where collection risk is growing.
Read receivables beside cash and supplier obligations
A large receivable balance can look strong until supplier payments are due first.
Belvara helps keep the wider business picture close so customer credit can be understood in context.
Belvara view: Receivables should answer three questions instantly: who owes you, how much do they owe, and how long have you already been waiting?
Do not let unpaid sales become invisible success
A credit sale feels like a win.
The customer said yes.
The invoice is large.
Revenue goes up.
Maybe profit goes up too.
But the business has not finished the job.
There is one final conversion left:
Receivable → Cash
Until that happens, the customer is holding part of the business’s working capital.
Sometimes that is deliberate.
Sometimes it is profitable.
Sometimes credit is necessary to win the customer.
But it should never be invisible.
A sale you cannot collect is not a better sale because the invoice was bigger.
The takeaway
Accounts receivable are amounts customers owe the business for goods or services already provided.
They are assets.
They are not cash.
That distinction matters because a business can:
- grow revenue
- report profit
- issue large invoices
- win bigger customers
and still struggle to pay its own bills if customer cash arrives too slowly.
The headline number is not enough.
You need to know:
- who owes you
- how much
- when it is due
- how old the balance is
- what has been paid
- what remains
- whether one customer holds too much of the total
The wrong question is:
“How much did we sell?”
The better question is:
“How much of what we sold has actually become cash?”
That is where accounts receivable stops being an accounting line and becomes a cash-control system.
Frequently Asked Questions About Accounts Receivable
What are accounts receivable in simple terms?
Accounts receivable are amounts customers owe a business for goods or services already provided but not yet paid for.
What does A/R mean?
A/R is a common abbreviation for accounts receivable.
Is accounts receivable an asset?
Yes. Accounts receivable are generally current assets when the business expects to collect them within the normal operating cycle or relevant short-term period.
Is accounts receivable cash?
No. Accounts receivable represent money customers owe. The amount becomes cash only when the customer pays.
Is accounts receivable revenue?
No. Revenue and accounts receivable are different. A credit sale can create revenue and a receivable at the same time.
What is the difference between accounts receivable and accounts payable?
Accounts receivable are amounts customers owe the business. Accounts payable are amounts the business owes suppliers.
What is an accounts receivable ageing report?
It is a report that groups unpaid customer balances by how long they have been outstanding.
Why is receivable ageing important?
Older balances can carry greater collection risk and deserve closer follow-up.
What is a bad debt?
A bad debt is an amount owed by a customer that the business does not expect to collect fully.
What is an allowance for doubtful accounts?
It is an accounting estimate used to reflect expected credit losses on receivables, subject to the applicable financial reporting framework.
What is accounts receivable turnover?
Accounts receivable turnover measures how often average receivables are collected during a period.
What is DSO?
DSO means Days Sales Outstanding. It estimates the average number of days it takes a business to collect receivables.
What is a good DSO?
There is no universal good DSO. It should be read against the business’s agreed customer payment terms, industry and collection model.
Can revenue rise while accounts receivable gets worse?
Yes. Revenue can grow while a larger share of sales remains unpaid or overdue.
Can a profitable business have cash problems because of receivables?
Yes. Profit can be positive while customer payments arrive too slowly to cover current cash needs.
Are partial payments still accounts receivable?
Yes. The unpaid portion generally remains receivable until it is settled or otherwise resolved.
Are customer deposits accounts receivable?
No. A customer deposit is generally money the business has already received and may create a liability until the related obligation is fulfilled. Accounts receivable are amounts the customer still owes the business.
How can a business reduce accounts receivable?
A business can tighten credit terms, invoice faster, follow up consistently, set credit limits, collect deposits, use payment schedules and stop extending further credit where risk becomes too high.
How does Belvara help with accounts receivable?
Belvara helps keep customer sales, payments and outstanding balances closer together so the owner has clearer visibility over who owes money, what has been paid and what remains outstanding.
What should I learn after accounts receivable?
Useful next concepts include accounts payable, working capital, cash flow, current assets, DSO, bad debts, credit control and the cash conversion cycle.
