
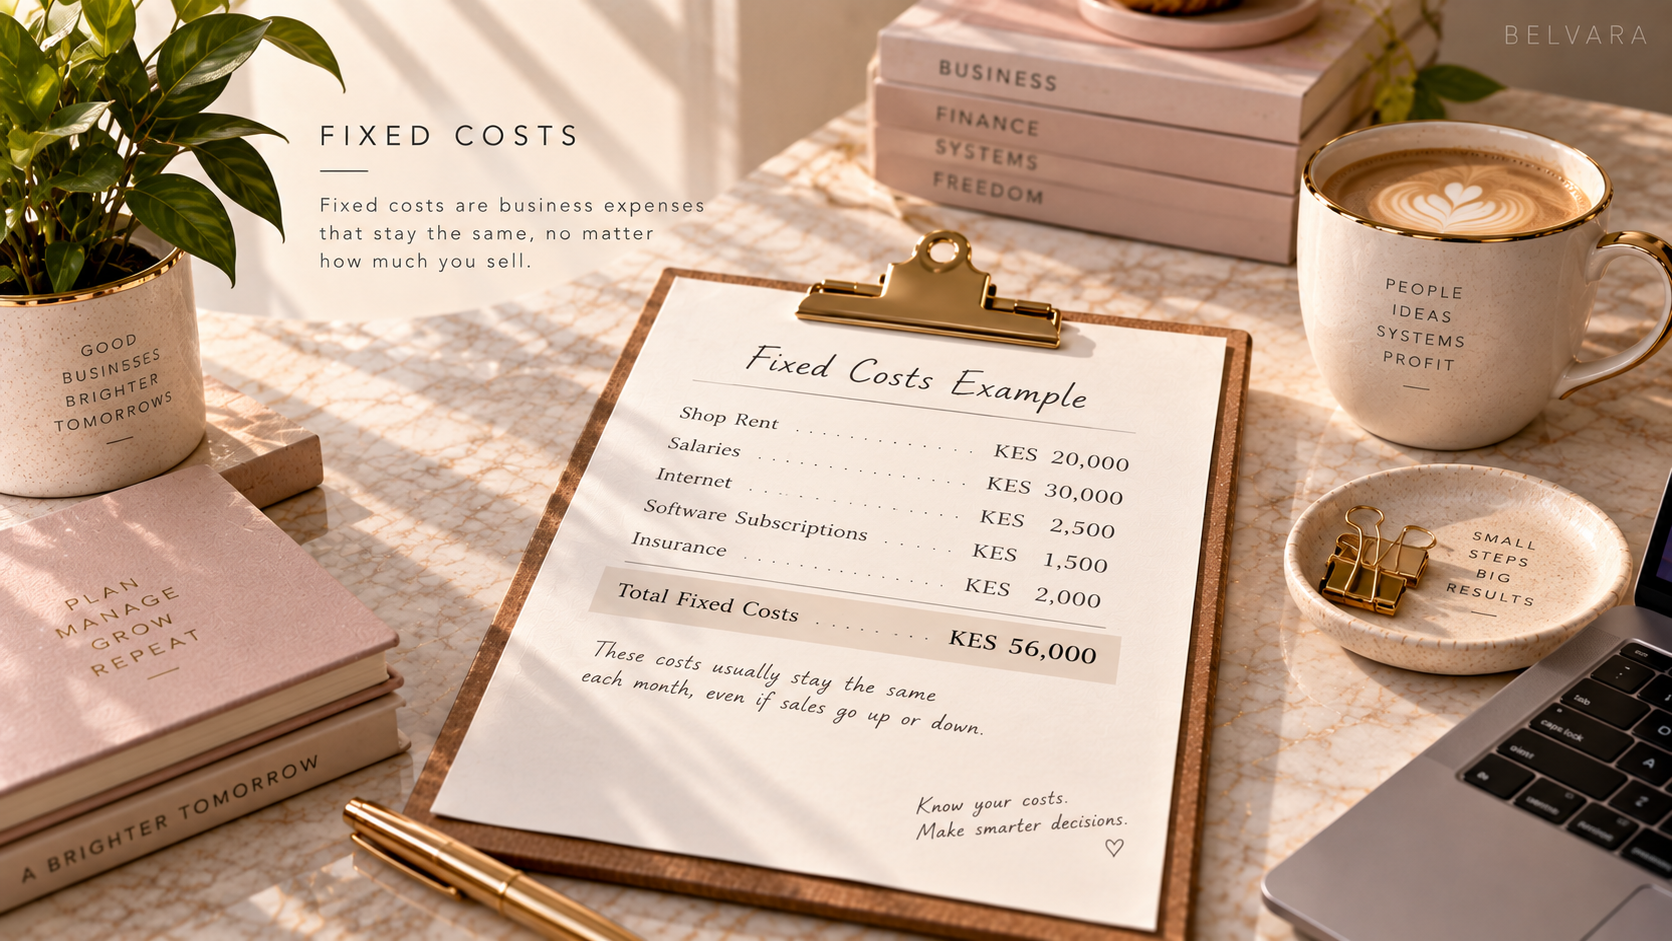
Your customers can disappear. Your sales can drop. Your bills don’t.
A slow month does not lower your rent.
Payroll still runs.
Subscriptions still renew.
Insurance is still due.
The business can get quieter overnight while the cost of keeping it open barely moves.
Those are fixed costs.
That is the pressure fixed costs create.
They are the costs a business usually has to carry even when sales move up or down in the short term.
That does not make fixed costs bad.
A shop gives you somewhere to sell.
A salaried team gives you capacity.
Software can save hours of manual work.
Insurance can protect the business.
But fixed costs create a minimum weight the business has to carry before profit becomes possible.
The more fixed cost you commit to, the more business has to happen just to justify the structure.
Belvara view: Fixed costs are not dangerous because they stay the same. They are dangerous because your sales do not.
What are fixed costs?
Fixed costs are costs that do not usually change directly with the number of units sold or the level of activity in the short term.
Common examples can include:
- shop or office rent
- salaried administrative payroll
- insurance
- licences
- some software subscriptions
- fixed retainers
- certain security or cleaning contracts
- some recurring premises costs
- depreciation, depending on the asset and accounting treatment
If sales increase this week, these costs may not change immediately.
If sales fall next week, they may still remain.
That is what makes them fixed in relation to activity.
But “fixed” does not mean permanent.
It means the cost does not usually move directly with each unit sold over the period being analysed.
That distinction matters.
Fixed does not mean forever
A business owner hears “fixed cost” and may think:
“This amount never changes.”
That is not what fixed means.
Rent can increase when a lease changes.
Payroll can increase when you hire.
Insurance premiums can change.
Software can move to a higher plan.
A business can open another branch.
A warehouse can become larger.
The cost may change.
What makes it fixed is that it does not usually rise and fall with every sale in the short term.
Suppose monthly rent is:
KES 100,000
If you sell:
- 100 units
- 500 units
- 1,000 units
the rent may still be KES 100,000.
That is fixed-cost behaviour.
But when the lease is renewed, rent could become KES 120,000.
Still fixed.
Just at a new level.
A fixed cost can change. What makes it fixed is what causes it to change.
Fixed costs vs variable costs
This is the basic distinction.
Fixed costs do not usually change directly with each additional sale in the short term.
Variable costs change with the level of sales or activity.
Suppose a product sells for:
KES 2,000
The business pays:
- Product cost: KES 1,000
- Packaging per order: KES 100
- Transaction fee per sale: KES 40
Those costs move when orders move.
They are variable to the activity being measured.
Now suppose the business also pays:
- Rent: KES 80,000/month
- Salaried admin staff: KES 120,000/month
- Software: KES 20,000/month
- Insurance: KES 10,000/month
Those costs may remain even if the number of orders changes.
That is why they behave as fixed costs.
| Cost | If sales double, does the cost usually double immediately? | Typical behaviour |
| Product cost | Yes, if twice as many units are sold | Variable |
| Packaging per order | Usually | Variable |
| Transaction fee per sale | Usually | Variable |
| Shop rent | Usually no | Fixed |
| Salaried admin payroll | Usually no | Fixed |
| Monthly software plan | Usually no | Fixed |
The word usually matters.
Real businesses are messier than textbook categories.
Why fixed costs matter
Fixed costs create the part of the business that sales have to carry before operating profit can begin.
Suppose:
- Selling price per unit: KES 2,000
- Variable cost per unit: KES 1,200
- Contribution per unit: KES 800
- Monthly fixed costs: KES 240,000
Each sale contributes:
KES 800
towards fixed costs and then profit.
The business needs:
KES 240,000 ÷ KES 800 = 300 units
just to cover fixed costs.
At 300 units, the contribution created by sales is:
KES 240,000
That covers the fixed-cost base.
Operating profit is:
KES 0
Sell fewer than 300 units and the business does not create enough contribution to carry the fixed costs.
Sell more than 300 and additional contribution can begin to create operating profit.
Fixed costs are the reason “we made money on every sale” is not enough. The business still has to pay for existing.
Fixed costs and break-even
Fixed costs sit at the centre of break-even.
For a simple single-product business:
Break-Even Units = Fixed Costs ÷ Contribution Margin per Unit
Suppose:
- Fixed costs: KES 300,000
- Contribution per unit: KES 1,000
Break-even:
300 units
Now fixed costs rise to:
KES 450,000
Contribution per unit stays:
KES 1,000
New break-even:
450 units
The business now needs 150 more unit sales before operating profit reaches zero.
Nothing changed about the product.
Nothing changed about the selling price.
Nothing changed about variable cost.
The fixed-cost structure changed the amount of sales the business needs to survive.
High fixed costs are not automatically bad
This is where lazy cost-cutting advice goes wrong.
High fixed costs can create useful capacity.
A larger warehouse may allow the business to hold more stock.
A salaried team may process more orders.
A second branch may reach a new market.
A better system may reduce errors.
A professional accountant may improve control.
The question is not:
“Are fixed costs high?”
The better question is:
“What capacity, control, revenue or protection do those fixed costs create?”
If a KES 200,000 monthly fixed cost helps create KES 600,000 of additional contribution, the cost may be excellent.
If a KES 20,000 fixed cost creates no value and nobody remembers why it exists, the smaller number may be the worse expense.
The size of a fixed cost does not tell you whether it is waste. Its relationship to business value does.
The danger is committing before demand proves itself
Fixed costs become risky when the business locks them in before sales are strong enough to carry them.
Suppose an online business currently has:
- Fixed costs: KES 100,000/month
- Average monthly contribution: KES 300,000
Operating contribution after fixed costs:
KES 200,000
The owner opens a physical shop.
New costs add:
- Rent: KES 120,000
- Salaried staff: KES 100,000
- Security and utilities: KES 30,000
New fixed costs:
KES 350,000/month
If contribution stays at KES 300,000, the business now loses:
KES 50,000
before other items.
The shop might eventually create enough new sales to justify itself.
But on day one, it raises the amount of contribution the business must generate every month.
A new branch does not start as growth. It starts as a fixed-cost promise that future sales have to keep.
Fixed costs create operating leverage
Operating leverage describes how a business with fixed costs can see profit move faster than sales once those fixed costs are covered.
That can work in both directions.
Suppose:
- Selling price: KES 2,000
- Variable cost: KES 1,000
- Contribution per unit: KES 1,000
- Fixed costs: KES 300,000
At 300 units:
Contribution:
KES 300,000
Operating profit:
KES 0
At 400 units:
Contribution:
KES 400,000
Operating profit:
KES 100,000
Sales increased by 100 units.
But fixed costs did not increase.
The extra KES 100,000 of contribution flows through to operating profit in this simplified example.
That is the good side of fixed costs.
Now go backwards.
At 250 units:
Contribution:
KES 250,000
Operating loss:
KES 50,000
When sales fall, the fixed costs stay.
That is the other side.
Fixed costs can make profit grow faster in a strong month and disappear faster in a weak one.
A quiet month exposes the fixed-cost base
Imagine two businesses selling the same type of product.
Business A
Monthly fixed costs:
KES 100,000
Business B
Monthly fixed costs:
KES 400,000
Both normally generate:
KES 600,000 of monthly contribution
In a normal month:
Business A has:
KES 500,000
left after fixed costs.
Business B has:
KES 200,000
left after fixed costs.
Now contribution falls to:
KES 250,000
Business A still has:
KES 150,000
after fixed costs.
Business B has:
KES 150,000 operating loss
The same weak month hits them differently because the structures are different.
Revenue did not tell you that.
The fixed-cost base did.
Rent is fixed until the business outgrows it
Rent is one of the clearest fixed-cost examples.
Suppose a shop pays:
KES 80,000/month
Whether it sells 200 units or 500 units, the rent may stay KES 80,000.
But now demand grows.
The business needs a larger location.
New rent:
KES 150,000
Rent has stepped up.
This is why fixed costs can behave in levels.
Within one range of activity, the cost stays fixed.
Once capacity changes, the cost jumps.
This is often called a step cost.
The business did not pay a little more rent for every extra unit.
It reached a point where the old space was no longer enough.
Then the fixed-cost structure changed.
Some costs are semi-variable
Not every cost fits neatly into fixed or variable.
Some contain both.
Suppose an electricity bill has:
- a fixed monthly standing charge
- a usage-based charge
Part of the bill is fixed.
Part is variable.
Or suppose a software platform charges:
- KES 10,000/month base fee
- plus KES 50 per transaction
Again, part is fixed.
Part moves with activity.
These are sometimes called mixed or semi-variable costs.
Trying to force them entirely into one category can weaken forecasting.
Salaries are not always fixed in the same way
A salaried employee may be a fixed cost over a short planning period.
But payroll becomes more complicated as the business grows.
Suppose one customer-service employee can handle:
500 orders per month
The business grows to:
900 orders
Payroll may stay unchanged.
Then orders reach:
1,100
The business hires another employee.
Payroll jumps.
The cost behaves like a step.
This is why “staff cost is fixed” can be useful for one analysis and misleading for another.
The period and activity range matter.
Fixed costs per unit fall as volume rises
The total fixed cost may stay the same.
But the amount of fixed cost carried by each unit changes with volume.
Suppose rent is:
KES 100,000/month
If the business sells:
100 units
Rent per unit is:
KES 1,000
If it sells:
500 units
Rent per unit is:
KES 200
If it sells:
1,000 units
Rent per unit is:
KES 100
The total rent never moved.
The cost per unit fell because the fixed cost was spread across more sales.
That is one reason scale can improve economics.
But only if demand exists.
Increasing capacity without increasing enough sales can do the opposite.
Low sales make fixed costs heavier
The same calculation works backwards.
Suppose fixed costs are:
KES 300,000
At 1,000 units:
Fixed cost per unit:
KES 300
At 500 units:
Fixed cost per unit:
KES 600
At 250 units:
Fixed cost per unit:
KES 1,200
The business did not become more expensive because rent suddenly doubled.
It became more expensive per unit of activity because fewer sales were carrying the same structure.
When sales fall, fixed costs do not get bigger. They get heavier.
Fixed costs can turn a good gross margin into a weak operating margin
Suppose:
- Revenue: KES 2,000,000
- COGS: KES 1,200,000
- Gross profit: KES 800,000
- Gross margin: 40%
Now the business carries:
- Rent: KES 180,000
- Salaried payroll: KES 300,000
- Software: KES 50,000
- Insurance: KES 20,000
- Other fixed overhead: KES 100,000
Total fixed operating costs:
KES 650,000
Before considering other relevant operating costs, only:
KES 150,000
of the KES 800,000 gross profit remains.
The gross margin looked strong.
The operating structure was heavy.
This is why a business can have good product economics and weak company economics.
Fixed costs and pricing
Pricing should know the fixed-cost structure exists.
Suppose a product creates:
KES 300 contribution per unit
and the business has:
KES 600,000 fixed monthly costs
Break-even volume:
2,000 units
Now suppose the business normally sells only:
900 units
That gap matters.
The owner can:
- increase price
- reduce variable cost
- reduce fixed cost
- sell more units
- improve product mix
- change the model
What the owner cannot do is pretend the fixed-cost base is irrelevant because the product is sold above cost.
A price is not commercially strong just because it clears product cost. It also has to leave enough contribution for the business around the product.
Fixed costs and discounts
Discounts can make fixed costs harder to carry.
Suppose:
- Selling price: KES 2,000
- Variable cost: KES 1,200
- Contribution: KES 800
- Fixed costs: KES 240,000
Break-even:
300 units
Now offer a 20% discount.
New selling price:
KES 1,600
Variable cost stays:
KES 1,200
Contribution falls to:
KES 400
The fixed costs did not change.
But break-even becomes:
600 units
The business now needs twice as many sales to carry the same fixed-cost base.
A discount does not reduce your rent. It reduces the amount each sale contributes towards paying it.
Fixed costs and seasonality
Seasonal businesses need to understand fixed costs especially well.
Suppose sales are strong in:
- November
- December
- January
and weak in:
- February
- March
- April
Rent may be due every month.
Salaried payroll may continue.
Insurance may continue.
Software may continue.
The business needs to understand whether strong months generate enough contribution to carry weak months.
A profitable December does not automatically make March safe.
Fixed costs and cash runway
Fixed costs also matter to cash planning.
Suppose the business has:
KES 1,200,000 cash available
and monthly fixed cash commitments of:
KES 300,000
Ignoring other inflows and outflows, that is roughly:
4 months
of fixed-cost coverage.
This is not a full cash-runway calculation.
Variable costs, debt payments, taxes, stock purchases, receivables and other cash movements still matter.
But fixed commitments give the owner a useful view of how quickly cash can be consumed if sales weaken.
Fixed cost is not the same as OPEX
Many fixed costs are operating expenses.
But the terms are not identical.
Fixed cost describes how a cost behaves when activity changes.
OPEX describes a category of operating expense.
An operating expense can be fixed, variable or mixed.
For example:
- Rent may be fixed OPEX.
- A sales commission may be variable OPEX.
- A utility bill may be mixed OPEX.
Different question.
Different classification.
Fixed cost is not the same as CapEx
Buying a long-term asset is not automatically a fixed cost.
Suppose the business purchases:
KES 500,000 of equipment
That may be capital expenditure.
The asset may then create depreciation expense over time, depending on accounting treatment.
The depreciation expense can behave like a fixed cost over the relevant period.
But the original capital purchase and the ongoing expense recognition are not the same thing.
This is why accounting labels should not be mixed casually.
Fixed cost is not the same as a fixed payment
A monthly cash payment can look fixed without being a fixed cost in profit analysis.
For example, loan principal repayments use cash but are not normally treated as an operating expense in the income statement.
Interest expense is different again and may be classified outside operating expenses depending on the reporting framework.
So this statement is too loose:
“Anything I pay every month is a fixed cost.”
Frequency of payment does not decide cost behaviour or accounting classification.
Fixed costs by branch
A company-wide total can hide where fixed commitments sit.
Suppose:
Branch A
- Fixed costs: KES 180,000
- Monthly contribution: KES 350,000
Amount after fixed costs:
KES 170,000
Branch B
- Fixed costs: KES 300,000
- Monthly contribution: KES 320,000
Amount after fixed costs:
KES 20,000
Branch B is carrying much more structure for only slightly less contribution.
That does not automatically make the branch bad.
It may be new.
It may have strategic value.
But the owner should know how much contribution each branch needs before it becomes worth carrying.
Fixed costs for an online business
Online does not mean low fixed cost forever.
An online merchant may start with:
- phone
- home storage
- social media
- simple software
Then grow into:
- warehouse rent
- salaried fulfilment staff
- customer-service staff
- paid systems
- insurance
- office costs
- retainers
The business can move from a light cost structure to a heavy one without noticing how much its minimum monthly burden has changed.
Growth can turn yesterday’s optional expense into tomorrow’s fixed commitment.
Fixed costs for a retail business
Common fixed or relatively fixed retail costs can include:
- shop rent
- salaried staff
- security
- insurance
- licences
- certain utilities
- software subscriptions
- cleaning contracts
A store with high foot traffic may carry these costs comfortably.
A slow location may struggle with the same structure.
The rent bill does not know how many customers walked in.
Fixed costs for a wholesale business
A wholesaler may carry fixed costs such as:
- warehouse rent
- salaried operations staff
- administration
- software
- insurance
- licences
- management costs
Because wholesale can work on thinner contribution per sale, volume becomes important.
A large warehouse can support scale.
It can also become an expensive promise if volume does not arrive.
Fixed costs for a service business
Service businesses can carry fixed costs even without inventory.
Examples may include:
- office rent
- administrative salaries
- software
- insurance
- licences
- recurring professional costs
A salon, agency, consultancy, clinic or repair business may also have capacity-related fixed or step costs.
If a team can handle only a certain number of clients, growth may require another hire or location.
That changes the fixed-cost structure.
What is a good level of fixed costs?
There is no universal answer.
A good fixed-cost structure depends on:
- contribution margin
- demand stability
- industry
- business model
- growth stage
- seasonality
- cash reserves
- capacity
- operating risk
- flexibility of commitments
The useful questions are:
- Can current contribution carry the fixed costs?
- How far above break-even are we?
- What happens if sales fall 20%?
- Which fixed costs create capacity?
- Which fixed costs exist out of habit?
- How quickly can a commitment be reduced if the business changes?
- Are we adding fixed costs ahead of proven demand?
- What sales level justifies the next hire, branch or warehouse?
The goal is not zero fixed costs.
The goal is a fixed-cost base the business can defend.

Common fixed-cost mistakes
1. Thinking fixed means permanent
Fixed costs can change. They simply do not usually change directly with every unit sold.
2. Treating every monthly payment as a fixed cost
Payment frequency does not determine accounting classification or cost behaviour.
3. Ignoring step costs
A cost can remain fixed until the business crosses a capacity threshold and then jump.
4. Adding fixed costs before demand is proven
A bigger structure creates a bigger minimum burden.
5. Looking at fixed costs only in total
Fixed cost per unit changes dramatically when volume changes.
6. Assuming high fixed costs are automatically bad
Some fixed costs create valuable capacity, control or growth.
7. Cutting useful capacity just to lower the number
A lower cost base can produce a weaker business.
8. Ignoring seasonality
Weak months still have to carry fixed commitments.
9. Forgetting how discounts affect fixed-cost coverage
Fixed costs stay while contribution per sale can fall.
10. Mixing fixed cost with OPEX or CapEx
These classifications answer different questions.
How to manage fixed costs better
Know the monthly base
Understand the costs that continue even when sales slow down.
Separate committed from flexible spending
A one-month campaign is different from a three-year lease.
Stress-test a weak month
Ask what happens if contribution falls by:
- 10%
- 20%
- 30%
Link every major fixed cost to a reason
What does the warehouse enable?
What does the salaried role produce?
What does the system protect?
Review capacity before adding more
Do not hire, expand or move simply because growth feels exciting.
Understand when current capacity actually becomes insufficient.
Compare the cost with the contribution needed to carry it
A KES 100,000 new fixed cost requires additional contribution.
Know how much.
Review old commitments
A fixed cost that made sense two years ago may no longer deserve automatic renewal.
How Belvara helps you keep fixed costs visible
Fixed costs become easy to ignore because they are familiar.
Rent happens every month.
Payroll happens every month.
Subscriptions renew.
Retainers continue.
The repetition can make them disappear into routine.
Belvara helps keep relevant operating records closer together so the owner can see the fixed-cost structure in the wider context of sales, expenses, payroll, branches and other business activity.
See the monthly cost base more clearly
Keeping recurring operating records organised makes it easier to understand what the business has committed to carry before variable activity is considered.
Read fixed costs beside contribution and sales
A KES 300,000 fixed-cost base means something very different in a business generating KES 1,000,000 of contribution than in one generating KES 320,000.
The cost needs context.
See when expansion raises the minimum
A new branch, warehouse, salaried role or recurring system can raise the amount of contribution the business needs every month.
Keeping those changes close to operating performance makes the impact easier to understand.
Compare locations and operating areas
Where relevant records are available, branch-level sales and expenses can help reveal which parts of the business are carrying their fixed structure and which are relying on stronger areas to cover them.
Belvara view: Fixed costs become dangerous when they turn invisible. The business should know what it has promised to pay before it celebrates what it hopes to sell.
Do not build a business that only works in a good month
The easiest time to justify a fixed cost is when sales are strong.
The larger shop feels obvious.
The extra hire feels overdue.
The annual subscription feels small.
The warehouse feels necessary.
Then demand slows.
That is when the commitment becomes real.
A resilient business does not assume every month will behave like its best month.
It understands:
- the fixed-cost base
- the break-even point
- the margin of safety
- the capacity those costs create
- how quickly costs can be changed if reality changes
Fixed costs are not the enemy.
Blind commitments are.
A strong business does not avoid fixed costs. It makes sure the fixed costs earn the right to stay fixed.
The takeaway
Fixed costs are costs that do not usually change directly with the level of sales or activity in the short term.
Examples can include:
- rent
- salaried administrative payroll
- insurance
- some software subscriptions
- licences
- certain recurring overheads
But fixed does not mean permanent.
It means the cost is not directly driven by every extra unit sold within the relevant range and period.
That matters because sales can move quickly while fixed costs remain.
A business can:
- have good products
- make contribution on every sale
- grow into a bigger space
- hire more people
- add better systems
and still make itself financially fragile if the fixed-cost base grows faster than the contribution available to carry it.
So the better question is not:
“How much are our fixed costs?”
It is:
“What do these fixed costs give us, how much contribution do they require, and can the business still carry them in a weak month?”
That is where fixed costs stop being a list of bills and become a structural business decision.
Frequently Asked Questions About Fixed Costs
What are fixed costs in simple terms?
Fixed costs are costs that do not usually change directly with the number of units sold or level of activity in the short term.
What are examples of fixed costs?
Examples can include rent, salaried administrative payroll, insurance, licences, some software subscriptions and certain recurring overheads.
Is rent a fixed cost?
Rent is commonly treated as a fixed cost over the relevant lease period because it does not usually change directly with the number of sales.
Is salary a fixed cost?
A salary can behave as a fixed cost over a short planning period, but payroll can become a step cost when additional staff are required as activity grows.
Is electricity a fixed cost?
Electricity can be mixed. Some charges may be fixed while usage changes with activity.
Is insurance a fixed cost?
Insurance premiums are commonly treated as fixed over the period covered because they do not usually change directly with each sale.
Is software a fixed cost?
A flat monthly software subscription can behave as a fixed cost. Usage-based software may be variable or mixed.
Are fixed costs the same as OPEX?
No. Fixed cost describes cost behaviour. OPEX describes operating expenses. OPEX can contain fixed, variable and mixed costs.
Are fixed costs the same as CapEx?
No. CapEx is spending on acquiring or improving long-term assets. Fixed cost describes how a cost behaves as activity changes.
Do fixed costs ever change?
Yes. Fixed costs can increase or decrease when leases change, staff are added, capacity expands or contracts are renegotiated.
What is a step cost?
A step cost stays fixed within a certain activity range, then jumps when the business needs additional capacity.
What is a semi-variable cost?
A semi-variable or mixed cost contains both a fixed component and a variable component.
Why do fixed costs matter for break-even?
Fixed costs determine how much contribution the business must generate before operating profit reaches zero.
How do fixed costs affect profit?
Once fixed costs are covered, additional contribution can increase profit more quickly. When sales fall, the same fixed costs can make losses appear quickly.
Are high fixed costs bad?
Not automatically. High fixed costs can support capacity, growth and control. The question is whether the business generates enough value to justify them.
How do discounts affect fixed costs?
Discounts do not usually reduce fixed costs. They can reduce contribution per sale, which means more sales may be needed to cover the same fixed-cost base.
What is fixed cost per unit?
Fixed cost per unit is total fixed cost divided by the number of units produced or sold. It falls as volume rises if total fixed cost stays unchanged.
How does Belvara help with fixed costs?
Belvara helps keep relevant operating records closer together, including expenses, payroll, sales, branches and other business activity. That gives the owner better context when recurring commitments increase or become harder for the business to carry.
What should I learn after fixed costs?
Useful next concepts include variable costs, contribution margin, break-even point, operating leverage, OPEX, gross margin and margin of safety.
