
A profitable business can still choke to death on working capital.
Revenue can be growing.
Profit can look healthy.
Customers can be ordering.
And the business can still struggle to buy stock, pay suppliers, make payroll or cover tax when it falls due.
That is what working capital exposes.
Working capital sits in the gap between doing business and getting the cash benefit from doing business.
A retailer buys stock before all of it sells.
A wholesaler lets customers pay later.
A service company pays staff before a client settles an invoice.
A growing business adds branches, inventory and people before the extra cash fully catches up.
On paper, the business may be doing well.
Operationally, it can be suffocating.
What is working capital?
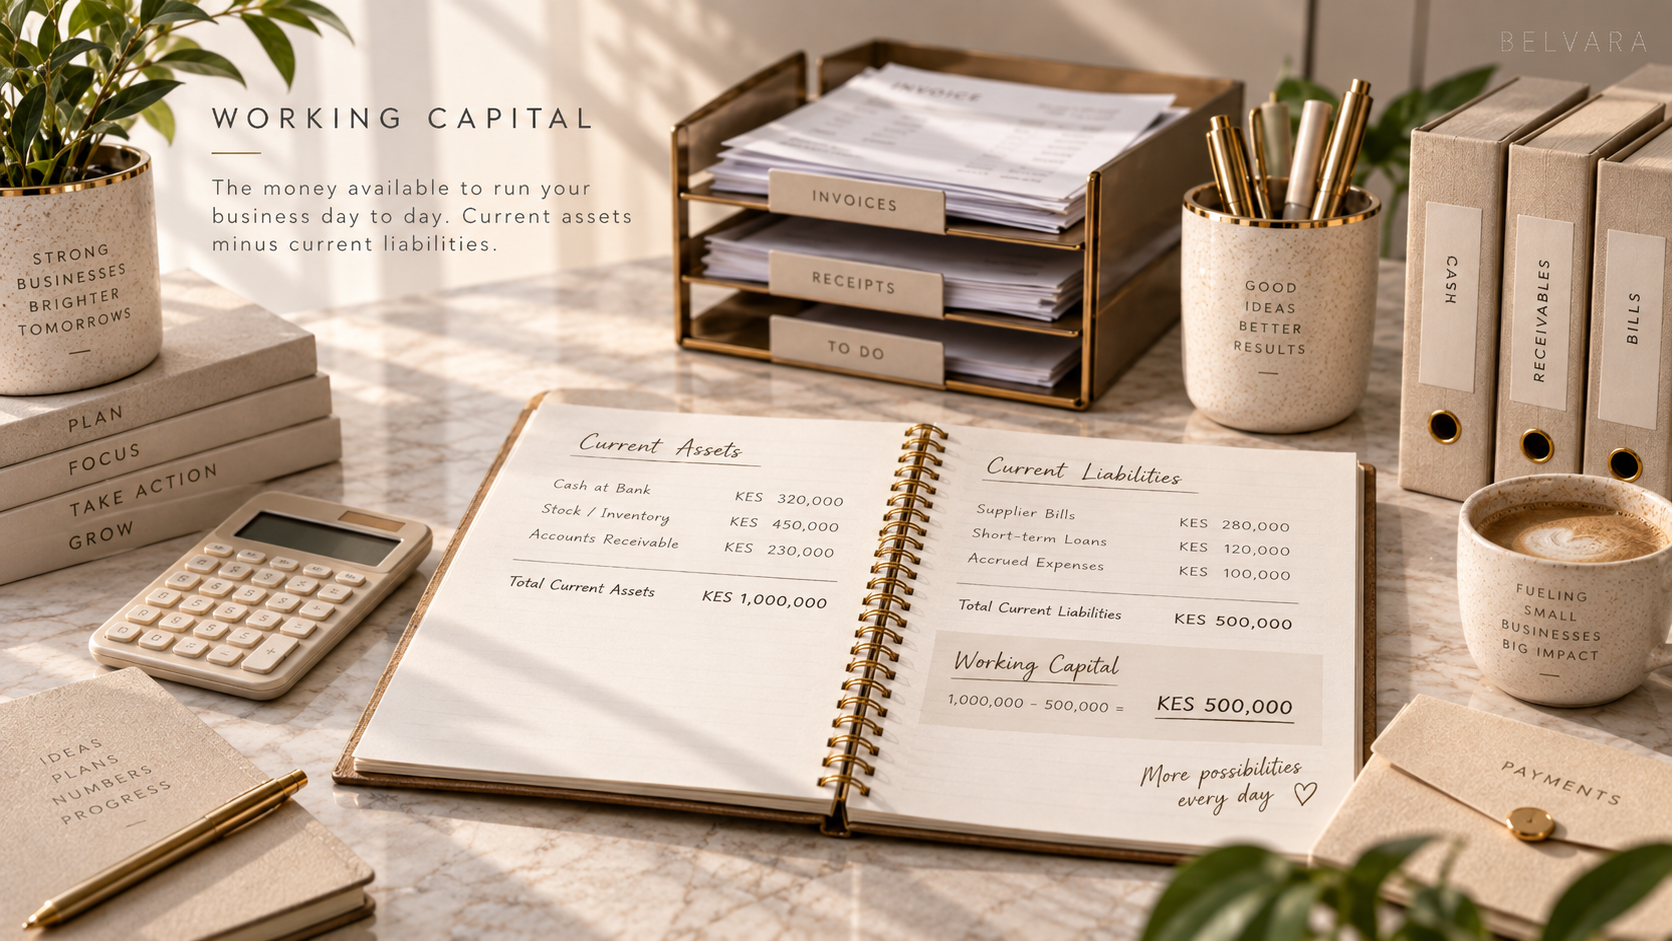
Working capital is the difference between a business’s current assets and current liabilities.
The basic formula is:
Working Capital = Current Assets − Current Liabilities
Current assets are short-term resources such as:
- cash and cash equivalents
- customer receivables
- inventory
- some short-term prepayments
- other assets expected to be realised, sold or consumed in the normal operating cycle
Current liabilities are short-term obligations such as:
- supplier balances
- accrued expenses
- payroll-related liabilities
- taxes due
- short-term borrowings
- other amounts expected to be settled in the normal operating cycle or within the relevant current period
Under IFRS presentation principles, items such as inventory, trade receivables and trade payables can form part of the entity’s normal operating cycle even when that cycle does not fit neatly inside twelve months.
In simple terms:
Working capital tells you how much short-term financial room the business has after short-term obligations are considered.
Belvara view: Profit tells you whether the business creates value. Working capital tells you whether the business can survive the timing.
The working capital formula
The standard formula is:
Working Capital = Current Assets − Current Liabilities
Suppose a business has:
Current assets
- Cash: KES 250,000
- Customer receivables: KES 300,000
- Inventory: KES 500,000
Total current assets = KES 1,050,000
Current liabilities
- Supplier balances: KES 400,000
- Payroll and accrued expenses: KES 150,000
- Taxes due: KES 100,000
Total current liabilities = KES 650,000
Working capital:
KES 1,050,000 − KES 650,000 = KES 400,000
The business has KES 400,000 positive working capital.
But that number needs context.
KES 500,000 of the current assets is inventory.
KES 300,000 is still owed by customers.
Only KES 250,000 is cash.
That means the business has positive working capital while most of it is not immediately spendable.
A positive working-capital number can still hide a cash problem if the “assets” are stock nobody is buying and invoices nobody is paying.
What are current assets?
Current assets are assets expected to be realised, sold, consumed or otherwise used within the normal operating cycle, or that meet other current-classification criteria.
For a growing business, the most important current assets usually include:
Cash
Money available in business bank accounts, qualifying cash equivalents and other cash balances.
Accounts receivable
Money customers owe the business for products or services already supplied on credit.
Inventory
Products, raw materials, work in progress or finished goods held for sale or production.
Prepayments
Amounts already paid for certain goods or services that relate to future periods.
Other current assets
Other short-term resources depending on the business.
Not all current assets are equally useful when the business needs cash quickly.
KES 300,000 in the bank is different from KES 300,000 in slow-moving stock.
That distinction becomes critical when assessing liquidity.
What are current liabilities?
Current liabilities are obligations expected to be settled within the business’s normal operating cycle or that otherwise meet current-classification criteria.
Common examples include:
Accounts payable
Money owed to suppliers for goods or services received.
Accrued expenses
Costs already incurred but not yet paid.
Payroll obligations
Salaries, wages and related amounts that are due.
Taxes and statutory obligations
Amounts due to tax or other authorities.
Short-term borrowings
Borrowings or portions of borrowings due in the short term.
Customer advances and contract liabilities
Money received before the related goods or services have been fully delivered, depending on the transaction.
Belvara view: A supplier invoice due Friday is not less real because the cash has not left yet. Working capital forces future obligations into today’s decisions.
Positive working capital
Positive working capital means current assets are greater than current liabilities.
Example:
- Current assets: KES 1,200,000
- Current liabilities: KES 800,000
Working capital:
KES 400,000
Positive working capital can suggest the business has short-term resources available to meet short-term obligations.
But positive does not automatically mean healthy.
The quality of those assets matters.
If most of the KES 1.2 million consists of:
- overdue receivables
- obsolete inventory
- stock that takes months to sell
the business may still struggle for cash.
Positive working capital is only comforting if the assets can actually turn into cash when the liabilities demand it.
Negative working capital
Negative working capital means current liabilities exceed current assets.
Example:
- Current assets: KES 700,000
- Current liabilities: KES 900,000
Working capital:
−KES 200,000
This can be a warning sign because short-term obligations exceed recorded short-term assets.
But negative working capital is not automatically fatal.
Some business models collect cash from customers very quickly while paying suppliers later.
Examples can include certain:
- supermarkets
- restaurants
- subscription businesses
- high-turnover retailers
- marketplaces with favourable settlement cycles
If customers pay immediately, inventory moves quickly and suppliers allow longer terms, the business can operate with low or even negative working capital.
The question is whether that position is structurally supported by the operating cycle or simply caused by financial stress.
Negative working capital can be a business model. It can also be a distress signal. The numbers look similar until you understand the operating cycle underneath them.
Working capital vs cash
Working capital is not the same as cash.
Working capital includes short-term assets and liabilities.
Cash is only one component.
Suppose a business has:
- Cash: KES 100,000
- Receivables: KES 400,000
- Inventory: KES 600,000
- Current liabilities: KES 700,000
Working capital:
KES 1,100,000 − KES 700,000 = KES 400,000
That sounds healthy.
But the business only has KES 100,000 in cash.
If KES 300,000 of supplier payments are due tomorrow, positive working capital will not automatically solve the immediate shortage.
The business needs inventory to sell or customers to pay.
Working capital can tell you the business has resources. Cash tells you whether those resources showed up in time.
Working capital vs cash flow
Working capital is a balance-sheet measure at a point in time.
Cash flow measures cash moving into and out of the business over a period.
They are connected.
Changes in working capital can absorb or release cash.
For example:
- receivables increasing can absorb cash
- inventory increasing can absorb cash
- payables increasing can temporarily preserve cash
- customers paying receivables can release cash
- inventory selling can release cash
- paying suppliers reduces cash and payables
This is why profitable growth can produce negative operating cash pressure.
The business may be building working capital faster than it is collecting cash.
Working capital vs profit
Profit tells you whether revenue exceeded the relevant costs and expenses.
Working capital tells you about short-term operating resources and obligations.
A business can be:
- profitable with weak working capital
- unprofitable with temporarily strong working capital
- profitable and cash-rich
- profitable and cash-starved
Example:
A wholesaler makes KES 300,000 profit this month.
But customers owe KES 800,000.
The wholesaler also owes suppliers KES 600,000.
The profit exists.
The cash timing is still dangerous.
Belvara view: Profit can reward a sale that working capital is still waiting to collect.
Working capital vs liquidity
Liquidity describes the business’s ability to meet short-term obligations.
Working capital is one way to assess that position.
But working capital alone does not tell the whole liquidity story because current assets differ in how quickly they can become cash.
That is why businesses also use measures such as:
- current ratio
- quick ratio
- cash ratio
- cash flow forecasts
What is the current ratio?
The current ratio compares current assets with current liabilities.
Formula:
Current Ratio = Current Assets ÷ Current Liabilities
Example:
- Current assets: KES 1,200,000
- Current liabilities: KES 800,000
Current ratio:
1.5
This means the business has KES 1.50 of current assets for every KES 1.00 of current liabilities.
A higher ratio can suggest more short-term coverage, but there is no universal “good” ratio for every business.
A company holding excessive slow-moving inventory can have a high current ratio and poor actual liquidity.
A ratio can look healthy because the warehouse is full. The supplier still wants cash.
What is the quick ratio?
The quick ratio is a stricter liquidity measure because it excludes inventory and certain other less-liquid current assets.
A common formula is:
Quick Ratio = (Cash + Short-Term Investments + Receivables) ÷ Current Liabilities
Suppose:
- Cash: KES 200,000
- Receivables: KES 300,000
- Inventory: KES 500,000
- Current liabilities: KES 600,000
Current ratio:
KES 1,000,000 ÷ KES 600,000 = 1.67
Quick ratio:
KES 500,000 ÷ KES 600,000 = 0.83
The difference tells a story.
The business looks comfortably covered when inventory is included.
Without inventory, its immediate liquidity is much tighter.
What is operating working capital?
Businesses and analysts sometimes distinguish operating working capital from broader working capital.
Operating working capital focuses more closely on short-term assets and liabilities created by normal business operations.
A common management approach focuses on items such as:
- trade receivables
- inventory
- trade payables
- other operating current assets and liabilities
Cash and financing items may be excluded depending on the definition being used.
There is no single universal management formula used by every company, so businesses should define operating working capital consistently.
The purpose is to understand:
How much capital is tied up in the day-to-day operating cycle?
Working capital asks how much short-term room you have. Operating working capital asks how much of that room the business model itself is consuming.
What is the working capital cycle?
The working capital cycle describes how cash moves through normal operations.
For a product business, the cycle often looks like:
Cash → Inventory → Sale → Receivable → Cash
The business:
- pays or commits money to stock
- holds that stock
- sells the stock
- may wait for the customer to pay
- eventually receives cash
At the same time, supplier payment terms affect when cash leaves.
The longer cash is trapped between paying suppliers and collecting customers, the more working capital the business needs.

What is the cash conversion cycle?
The cash conversion cycle (CCC) estimates how long cash is tied up in operations before returning to the business.
A common formula is:
Cash Conversion Cycle = Days Inventory Outstanding + Days Sales Outstanding − Days Payables Outstanding
Where:
- Days Inventory Outstanding (DIO) estimates how long inventory is held before sale
- Days Sales Outstanding (DSO) estimates how long customers take to pay
- Days Payables Outstanding (DPO) estimates how long the business takes to pay suppliers
Example
Suppose:
- DIO = 45 days
- DSO = 30 days
- DPO = 25 days
Cash conversion cycle:
45 + 30 − 25 = 50 days
The business’s cash is tied up in the operating cycle for approximately 50 days.
Fifty days is not just a ratio. It is fifty days the business has to finance the gap between paying for activity and getting its money back.
Working capital for a product-based business
Product businesses can consume huge amounts of working capital through inventory.
Suppose a retailer has:
- Cash: KES 150,000
- Customer receivables: KES 100,000
- Inventory: KES 900,000
- Current liabilities: KES 700,000
Working capital:
KES 1,150,000 − KES 700,000 = KES 450,000
On paper, positive.
Operationally, KES 900,000 is sitting in stock.
If KES 400,000 of that stock is slow-moving, the business has a working-capital quality problem.
Belvara view: Inventory is working capital wearing a barcode. The slower it moves, the longer your cash stays trapped inside it.
That is why Belvara’s future Business OS should not treat inventory as a separate department from finance.
Stock levels, purchasing, sales velocity, COGS, supplier terms and cash requirements all affect the same operating system.
Working capital for wholesalers
Wholesalers often face a brutal timing problem:
They pay suppliers before customers pay them.
Suppose a wholesaler:
- buys KES 1,000,000 of stock
- must pay the supplier within 14 days
- gives customers 30-day credit
The business may need to finance at least part of the timing gap.
If sales grow quickly, the problem can grow too.
More sales can mean:
- more stock purchases
- larger receivables
- larger supplier obligations
before the cash arrives.
Growth can increase your working-capital requirement faster than it increases your bank balance.
Working capital for service businesses
Service companies may carry little or no inventory.
Their working-capital pressure often comes from:
- client receivables
- payroll
- subcontractors
- project expenses
- taxes
- retainers
- milestone timing
Suppose an agency bills KES 800,000.
Clients will pay in 45 days.
Payroll of KES 350,000 is due this month.
Freelancers are owed KES 150,000.
The agency may be profitable while still needing KES 500,000 before the client cash arrives.
The business’s main working-capital asset may be receivables rather than inventory.
Working capital for subscription and SaaS businesses
Subscription businesses can have favourable working-capital dynamics when customers pay upfront.
For example, annual prepayments can provide cash before the full service is delivered.
That can reduce short-term financing pressure.
But SaaS businesses still have obligations such as:
- payroll
- infrastructure
- customer support
- tax
- refunds
- acquisition spend
A business that collects annually but spends aggressively can still create working-capital stress.
Upfront cash is breathing room, not permission to forget the obligations attached to it.
Working capital for restaurants and hospitality
Restaurants often collect from customers immediately while suppliers may allow some payment time.
That can create a favourable cash cycle.
But restaurants also face:
- perishable inventory
- payroll
- rent
- supplier bills
- taxes
- utilities
- equipment
- wastage
Fast collections do not eliminate working-capital risk if stock, waste and fixed costs are poorly controlled.
Working capital for manufacturers
Manufacturers can have working capital tied up across several stages:
- raw materials
- work in progress
- finished goods
- receivables
The business may pay for inputs months before collecting the final customer.
That can make the working-capital requirement substantial.
Long production cycles also mean more cash can become trapped before a sale is even possible.
Working capital for marketplaces
Marketplaces need to distinguish their own working capital from customer or merchant funds that may pass through settlement flows.
Relevant operating items can include:
- platform receivables
- merchant payables
- refunds
- commissions
- operating expenses
- timing of settlements
Money moving through the platform does not automatically belong to the business.
That distinction becomes essential if Belvara later supports marketplace, payment or settlement-heavy businesses.
How inventory affects working capital
Inventory is a current asset.
When a business buys stock:
- cash may decrease
- inventory increases
Total working capital may not change immediately if one current asset simply turns into another.
But liquidity changes.
Cash becomes less liquid inventory.
If the inventory sells slowly, the business may have less flexibility.
If it becomes obsolete, damaged or unsellable, its recoverable value can decline.
Turning cash into stock does not destroy working capital on paper. It can destroy flexibility in real life.
This is why stock quality matters as much as stock value.
How receivables affect working capital
Accounts receivable increase current assets.
That can make working capital look stronger.
But receivables are only useful if customers pay.
Suppose a company has:
KES 700,000 receivables
If KES 300,000 is more than 90 days overdue, the headline working-capital number may overstate the practical strength of the business.
Useful receivables questions include:
- Who owes us?
- How much?
- When was it due?
- How old is the balance?
- Is the customer still active?
- Is the balance disputed?
- What is realistically collectible?
An overdue receivable is not cash with patience. It is a risk that gets more expensive the longer you ignore it.
How payables affect working capital
Accounts payable reduce working capital because they are current liabilities.
But supplier credit can help preserve cash.
Suppose a supplier gives the business 30 days to pay.
The business receives inventory today but keeps its cash temporarily.
That can support the operating cycle.
However, stretching payables too far can damage:
- supplier relationships
- credit terms
- supply continuity
- pricing
- reputation
Supplier terms are working-capital tools. Supplier trust is the asset you burn when you abuse them.
How Lipa PolePole affects working capital
Partial-payment arrangements change the timing of customer cash.
Suppose a customer commits to a KES 30,000 purchase but pays:
- KES 10,000 today
- KES 10,000 next week
- KES 10,000 the following week
The business may have stock reserved against the order while only part of the cash has been collected.
That can create a working-capital trade-off.
The business gains:
- customer commitment
- partial cash collection
But it may also:
- reserve inventory
- delay a full-price cash sale to someone else
- carry the outstanding balance
- wait before dispatch
For Belvara’s Lipa PolePole workflow, the future operating view should connect:
- total order value
- amount paid
- outstanding balance
- expected collection dates
- reserved stock
- dispatch eligibility
- overdue instalments
Belvara view: Partial payment is not just a sales feature. The moment stock is reserved before cash is complete, it becomes a working-capital decision.
How supplier terms affect working capital
Supplier terms influence when cash leaves.
Imagine two businesses buying the same KES 500,000 inventory.
Business A
Pays supplier immediately.
Business B
Gets 30-day payment terms.
Business B keeps the KES 500,000 cash longer.
If it sells and collects enough inventory before the supplier falls due, the cycle is easier to finance.
But longer supplier terms should not be mistaken for free money.
The payment date still exists.
How customer payment terms affect working capital
Giving customers more time to pay increases receivables.
That can help win business.
It can also increase working-capital requirements.
Suppose a company grows sales from KES 1 million to KES 2 million by offering 60-day terms.
Revenue doubled.
But if an extra KES 700,000 is now sitting in receivables, the business may need additional financing to support the growth.
If growth requires you to lend more money to your customers, ask whether you are scaling sales or scaling receivables.
Why growth consumes working capital
Growth is one of the most dangerous times for working capital.
A growing business may need:
- more inventory
- more staff
- more supplier orders
- more warehouse space
- higher payroll
- more customer credit
- more branches
- more delivery capacity
before the related cash is collected.
Suppose a retailer grows monthly revenue from KES 800,000 to KES 1,600,000.
To support the new volume, it adds:
- KES 500,000 inventory
- KES 100,000 monthly payroll
- KES 150,000 receivables
The growth may be profitable.
But the business needs more working capital to carry it.
Belvara view: Growth does not only demand customers. Growth demands funding for the gap between doing more business and getting paid for it.
This is why a Business OS should show the operational cost of growth before the owner discovers it in the bank account.
Can too much working capital be bad?
Yes.
Very high working capital is not automatically efficient.
It can mean the business is holding:
- too much inventory
- excessive cash
- slow receivables
- underused short-term assets
Suppose a retailer has KES 2 million in inventory but sells only KES 300,000 per month.
The working-capital figure may be strongly positive.
The capital may still be poorly deployed.
Working capital is not a trophy. Idle working capital is money waiting for a better job.
The goal is not simply to maximise working capital.
It is to maintain enough high-quality working capital for the business model without trapping unnecessary capital.
What is working capital management?
Working capital management is the process of controlling short-term assets and liabilities so the business can operate efficiently and meet its obligations.
That can include managing:
- cash
- inventory
- receivables
- payables
- purchasing
- customer credit
- supplier terms
- short-term forecasts
Good working-capital management tries to answer:
- How much stock should we carry?
- How quickly are customers paying?
- Which balances are overdue?
- When are suppliers due?
- How much cash is available after commitments?
- What happens if sales grow?
- What happens if collections slow?
- What payments are coming next?
This is where Belvara’s future Business OS becomes strategically important.
Working capital is not owned by one menu item called Finance.
It is produced by decisions across the whole company.
How You Should Use Belvara’s Working Capital section
Belvara’s long-term opportunity is bigger than displaying:
Current Assets − Current Liabilities
Belvara helps explain why working capital moved.
That means connecting operational records such as:
Sales and customers
- orders
- sales
- invoices
- customer balances
- partial payments
- refunds
- payment dates
Inventory and purchasing
- purchase orders
- stock received
- stock on hand
- stock ageing
- slow-moving stock
- write-offs
- supplier costs
Suppliers
- amounts owed
- due dates
- payment terms
- purchase commitments
People and payroll
- salaries due
- payroll timing
- statutory obligations
Finance
- cash balances
- expenses
- taxes
- receivables
- payables
- cash-flow forecasts
Branches and operations
- stock by location
- sales by location
- expenses by location
- internal transfers
- upcoming commitments
Belvara view: Working capital is not a finance problem. It is what happens when sales, stock, suppliers, customers and cash stop talking to each other.
That is exactly why a Business OS has an advantage over disconnected point solutions.
The owner should not need to export:
- inventory from one app
- invoices from another
- M-Pesa from somewhere else
- supplier balances from a spreadsheet
- payroll from another tool
just to understand whether the business has enough room to operate.
The operating system should already understand the relationships.
What should a working-capital dashboard show?
A useful future Belvara working-capital view could surface:
- current cash position
- receivables outstanding
- overdue receivables
- inventory value
- slow-moving and dead stock
- supplier balances
- upcoming supplier payments
- payroll due
- taxes due
- expected customer collections
- projected short-term cash position
- current working capital
- current ratio
- quick ratio
- inventory days
- receivable days
- payable days
- cash conversion cycle
- large upcoming commitments
But the dashboard itself is not the product.
The value is in the system being able to explain:
What changed?
Why did it change?
What becomes due next?
What can the owner do about it?
Belvara view: A red working-capital warning after the cash is gone is reporting. A warning while there is still time to act is an operating system.
Working capital warning signs
A business should investigate when it sees patterns such as:
Receivables growing faster than sales
Customers are taking more of the growth home before paying for it.
Inventory growing faster than revenue
Cash may be getting trapped in stock.
More overdue supplier balances
The business may be financing operations by delaying suppliers.
Declining cash despite profit
Working capital may be absorbing operating cash.
Heavy dependence on owner injections
Normal operations may not be self-funding.
Constant emergency stock purchasing
Planning or forecasting may be weak.
Payroll pressure every month
The operating cycle may not produce cash at the right time.
Large tax obligations with no reserved cash
Money collected or earned has already been spent elsewhere.
If every month ends with “we made money, but where did it go?”, working capital is one of the first places to look.
How to improve working capital
There is no single fix.
The right lever depends on what is consuming capital.
1. Collect receivables faster
Possible actions include:
- clearer payment terms
- deposits
- partial payments
- automatic reminders
- stronger follow-up
- easier payment methods
- tighter customer credit
2. Reduce slow-moving inventory
Use sales velocity and demand data to avoid tying cash up in products that are not moving.
3. Improve purchasing
Order closer to real demand where practical.
4. Negotiate supplier terms
Better-aligned supplier terms can reduce timing pressure.
5. Protect gross margins
Weak margins leave less cash to support the operating cycle.
6. Forecast payroll, tax and supplier obligations
Known payments should not create surprise liquidity crises.
7. Review customer credit policies
A sale is not always worth having if the payment terms strain the business.
8. Control stock loss and write-offs
Lost inventory is lost working capital.
9. Plan growth
Estimate how much additional inventory, receivables and payroll growth will require.
10. Monitor the cycle continuously
Working capital can deteriorate long before the monthly accounts show obvious distress.
Common working capital mistakes business owners make
1. Looking only at the bank balance
Cash is only part of working capital.
2. Assuming positive working capital means strong liquidity
Inventory and overdue receivables may be difficult to convert into cash.
3. Treating all receivables as equally valuable
An invoice due tomorrow is not the same as an invoice six months overdue.
4. Treating all inventory as healthy
Dead stock can inflate current assets.
5. Ignoring supplier due dates
Payables have timing.
6. Growing without funding the operating cycle
More sales can require more capital before they generate cash.
7. Offering customer credit without measuring the cost
Longer payment terms have a financing effect.
8. Using supplier credit as permanent financing
Terms can change.
9. Mixing working capital with profit
They answer different questions.
10. Measuring the number without understanding the drivers
Belvara view: “Working capital is KES 400,000” is a report. “KES 180,000 is trapped in overdue invoices and KES 220,000 is trapped in slow stock” is management information.
A complete working capital example
Consider a growing homeware business.
Current assets
- Bank and M-Pesa cash: KES 250,000
- Customer receivables: KES 300,000
- Inventory: KES 700,000
- Prepayments: KES 50,000
Total current assets = KES 1,300,000
Current liabilities
- Supplier payables: KES 500,000
- Payroll and accruals: KES 180,000
- Taxes due: KES 120,000
- Short-term loan amount due: KES 100,000
Total current liabilities = KES 900,000
Working capital
KES 1,300,000 − KES 900,000 = KES 400,000
Positive working capital.
But now look underneath it.
Of the KES 300,000 receivables:
KES 150,000 is overdue.
Of the KES 700,000 inventory:
KES 250,000 has not sold in more than 120 days.
The KES 400,000 headline is technically useful.
The operating reality is much tighter.
A working-capital number without ageing, due dates and stock velocity is a photograph with half the picture cropped out.
This is the level of context Belvara should eventually provide.
The takeaway
Working capital is the difference between current assets and current liabilities.
The formula is:
Working Capital = Current Assets − Current Liabilities
But the formula is the least interesting part.
Working capital is really about the operating gap between:
- buying and selling
- selling and collecting
- receiving and paying suppliers
- earning profit and actually having cash
A business can have positive working capital and poor liquidity.
It can have negative working capital and a highly efficient operating model.
It can be profitable and still run out of cash because inventory and receivables are absorbing everything the business generates.
That is why working capital belongs at the centre of Belvara’s future Business OS.
The businesses that run out of working capital are not always failing businesses. Sometimes they are growing businesses that financed the gap badly.
Belvara should help owners see that gap while there is still time to manage it.
Not just:
“How much working capital do we have?”
But:
“Where is it tied up, what is due next, and what should we change before cash becomes the problem?”
Frequently Asked Questions About Working Capital
What is working capital in simple terms?
Working capital is the difference between a business’s current assets and current liabilities. It helps show the short-term resources available relative to short-term obligations.
What is the formula for working capital?
Working Capital = Current Assets − Current Liabilities
What are examples of current assets?
Common current assets include cash, receivables, inventory, some prepayments and other assets expected to be realised or consumed in the normal operating cycle.
What are examples of current liabilities?
Common current liabilities include supplier payables, accrued expenses, payroll obligations, taxes due and short-term borrowings.
What is positive working capital?
Positive working capital means current assets exceed current liabilities.
What is negative working capital?
Negative working capital means current liabilities exceed current assets. This can signal financial pressure, although some fast-cash business models can operate successfully with low or negative working capital.
Is working capital the same as cash?
No. Cash is one current asset. Working capital also includes items such as receivables and inventory and subtracts current liabilities.
Is working capital the same as cash flow?
No. Working capital is a balance-sheet measure at a point in time. Cash flow measures cash moving into and out of the business over a period.
Is working capital the same as profit?
No. Profit measures financial performance. Working capital measures short-term operating resources relative to short-term obligations.
Can a profitable business have poor working capital?
Yes. Profit can be tied up in receivables or inventory while suppliers, payroll, and other short-term obligations still require cash.
Can a business have too much working capital?
Yes. Excessive inventory, slow receivables, or unused cash can create high working capital while capital is being used inefficiently.
What is a good amount of working capital?
There is no universal ideal amount. The right level depends on the business model, operating cycle, industry, growth rate, supplier terms, customer terms and risk.
What is the current ratio?
Current Ratio = Current Assets ÷ Current Liabilities
It compares short-term assets with short-term liabilities.
What is the quick ratio?
The quick ratio is a stricter liquidity measure that generally excludes inventory and certain other less-liquid current assets.
What is operating working capital?
Operating working capital focuses on current assets and liabilities generated by normal operations, such as receivables, inventory, and trade payables. Definitions can vary by business.
What is the working capital cycle?
The working capital cycle describes how cash moves through business operations, often from cash to inventory, sale, receivables, and back to cash.
What is the cash conversion cycle?
The cash conversion cycle estimates how long cash is tied up in the operating cycle.
A common formula is:
CCC = Days Inventory Outstanding + Days Sales Outstanding − Days Payables Outstanding
How does inventory affect working capital?
Inventory increases current assets, but it can reduce liquidity because cash is tied up until the inventory sells and is collected.
How do receivables affect working capital?
Receivables increase current assets. However, overdue or uncollectible receivables can weaken the practical quality of working capital.
How do payables affect working capital?
Payables are current liabilities and therefore reduce net working capital. Supplier terms can temporarily help preserve cash.
How does growth affect working capital?
Growth often increases the need for inventory, receivables, payroll and supplier commitments before the extra customer cash is collected.
How can a business improve working capital?
Common levers include faster collections, better inventory management, stronger purchasing, appropriate supplier terms, improved margins, disciplined customer credit and short-term cash forecasting.
Why is working capital important for small businesses?
Small businesses often have limited cash buffers. A timing mismatch between customer payments, stock purchases, payroll and supplier obligations can therefore create problems quickly.
How should Belvara help with working capital?
As Belvara evolves into a Business OS, its role should be to connect the operational records that drive working capital: sales, payments, receivables, stock, purchasing, suppliers, payroll, taxes, expenses and expected obligations. The goal is not only to calculate working capital, but to explain what is consuming it and what is likely to happen next.
What should I learn after working capital?
The next useful concepts are accounts receivable, accounts payable, inventory turnover, current ratio, quick ratio, cash conversion cycle, liquidity and cash-flow forecasting.
